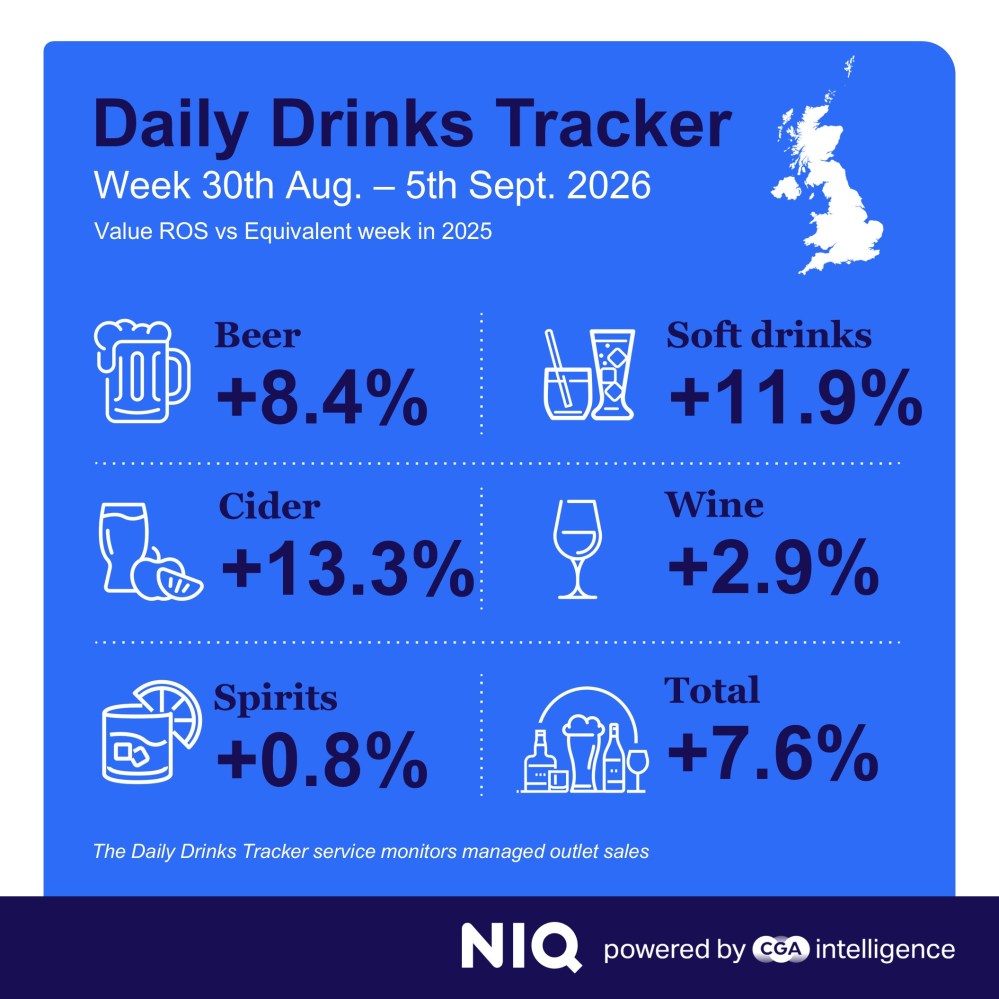
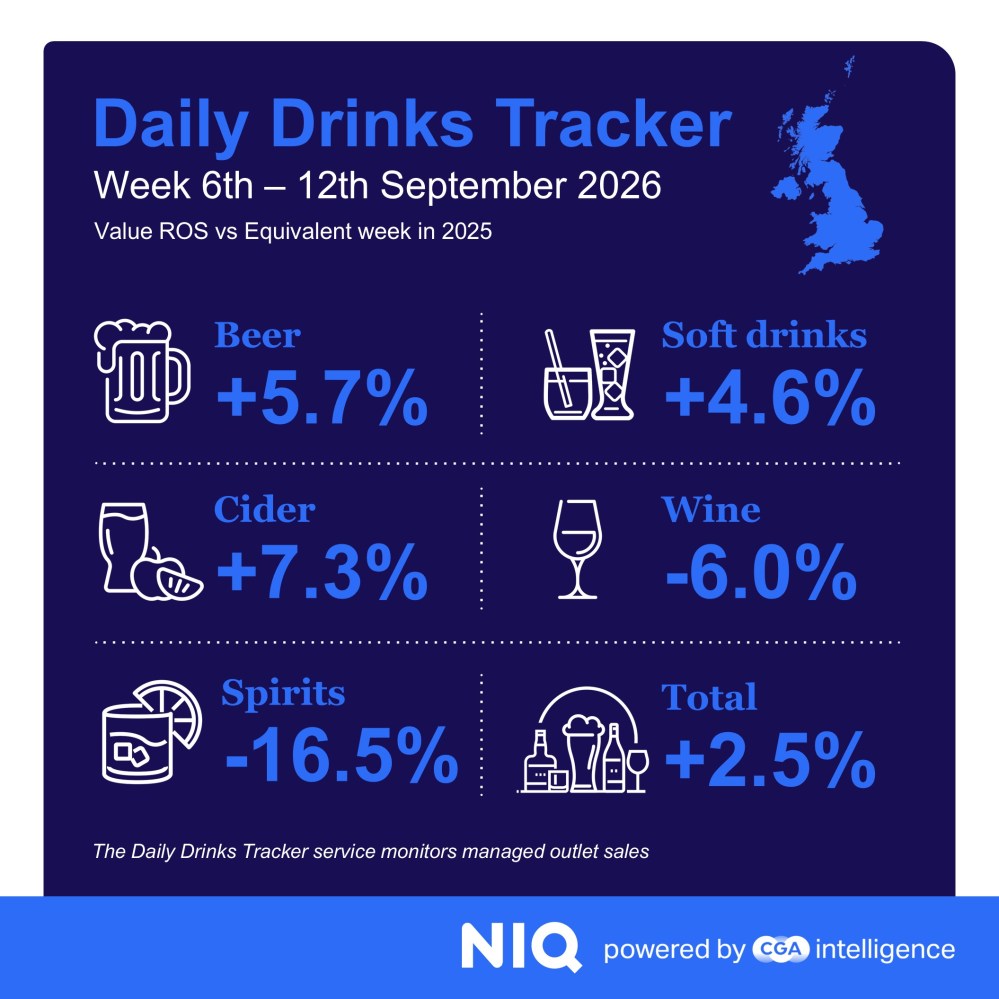
Average sales in managed venues in the week to Saturday 5 September were 7.6% ahead of the same week in 2025, thanks to a combination of good weather and the August Bank Holiday weekend. This was followed by solid growth of 2.5% in the next seven days to Saturday 12 September.
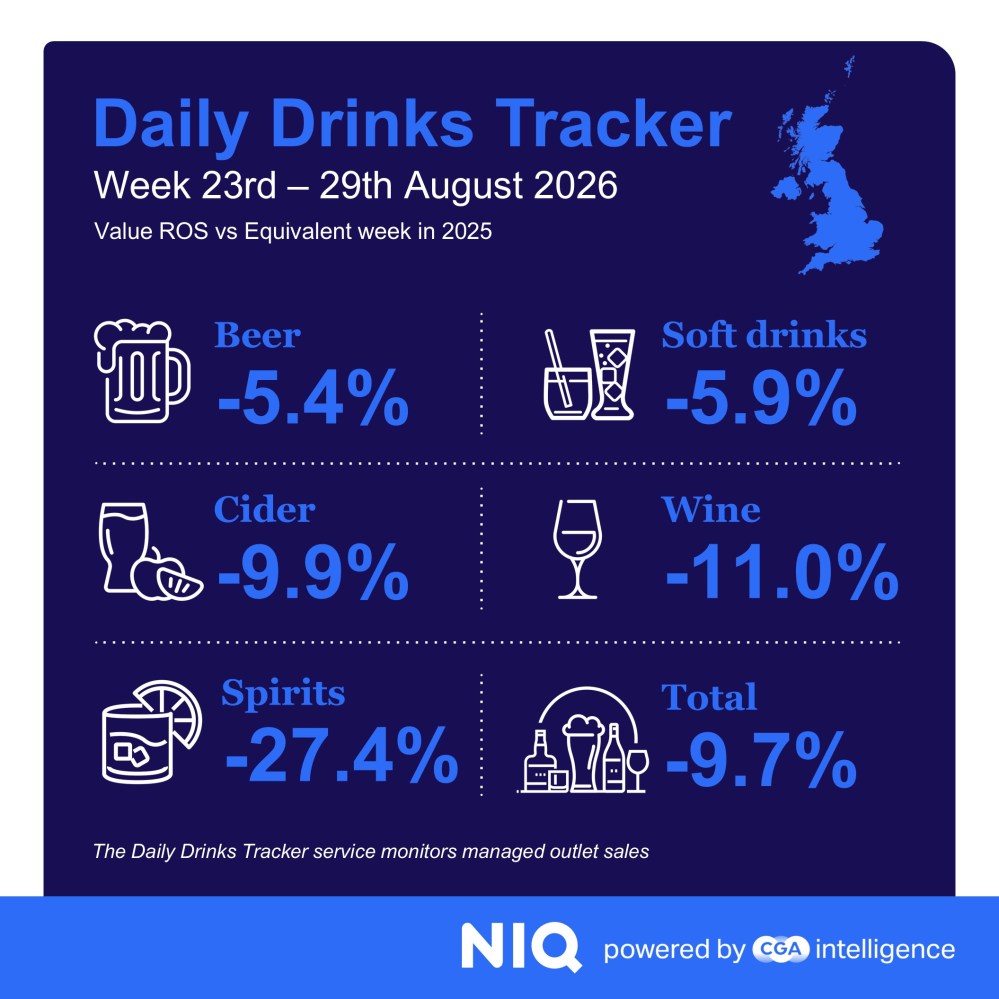
The upswing comes after a difficult August, when extreme heat kept some people away from the On-Premise. Sales in the week to Saturday 29 August fell 9.7% behind the same week last August. It was a sixth straight negative weekly number since the end of the football World Cup in mid-July, during which fans spent freely in pubs and bars.
The Daily Drinks Tracker, powered by CGA intelligence, indicates that the first fortnight of September was particularly strong for Long Alcoholic Drinks (LAD) suppliers, as consumers sought refreshment from long serves. Beer sales were up by 8.4% and 5.7% in the weeks to 5 and 12 September respectively. Cider fared even better, leaping by 13.3% and 7.3%. These two categories were also boosted by an attractive programme of football fixtures in the Premier League and Champions League.
It was also a good two weeks for soft drinks, which rose by 11.9% and 4.6% across the fortnight. However, wine (up 2.9% and down 6.0%) and spirits (up 0.8% and down 16.5%) were weaker.
The Tracker’s daily breakdown of trading shows a particularly buoyant August Bank Holiday weekend. Sales on Sunday and Monday (30 and 31 August) jumped 39.3% and 59.4% ahead of the same days in 2025, though these comparisons are skewed by an earlier Bank Holiday in 2025. Wednesday 9 September (up 15.9%) and Thursday 10 September (up 8.9%) were two other standout days.
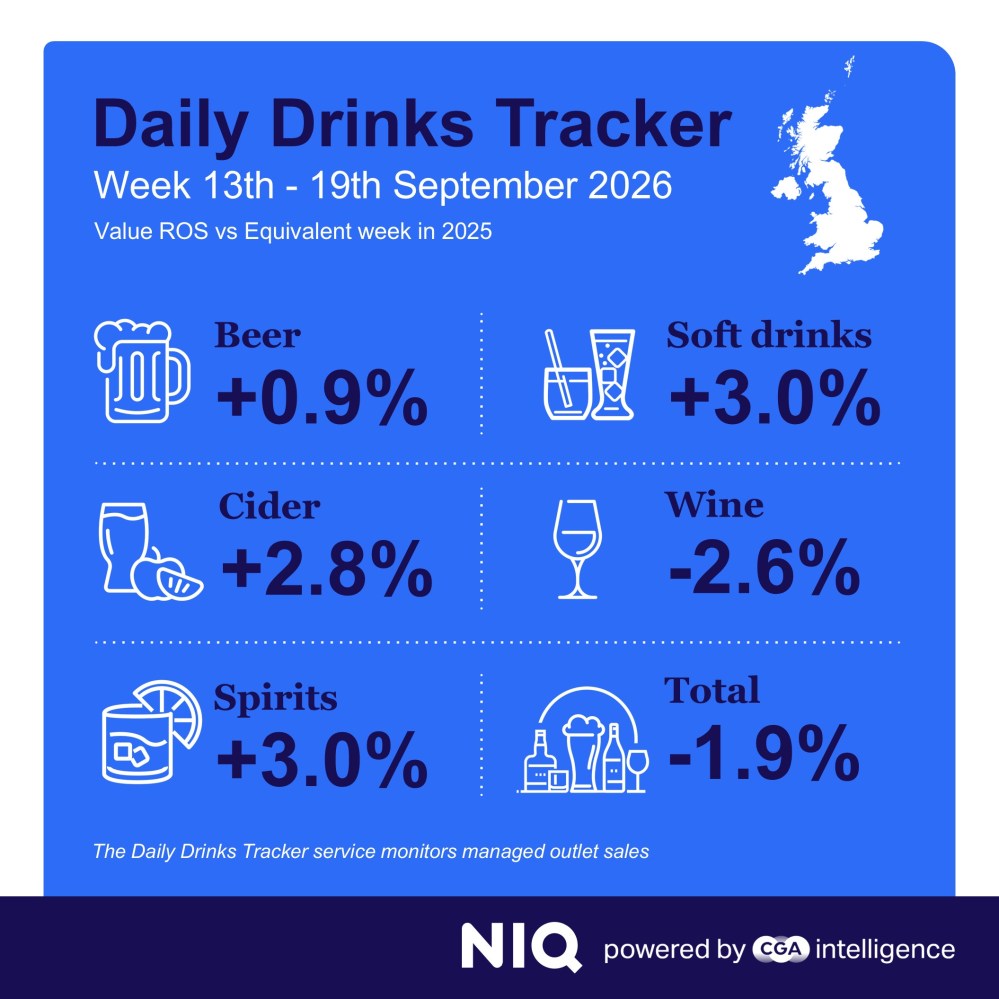
After a good start to September, trading slipped back in the third week of the month as cooler and wetter weather moved into many parts of Britain. Average sales in the seven days to Saturday 19 September were 2.0% down on the corresponding week in 2025.
Rachel Weller, NIQ’s commercial lead, UK & Ireland, said: “A good start to September will have been a relief to On-Premise operators and beer, cider and soft drinks brands. It has helped to claw back some of the ground that was lost in August, when extreme heatwaves, a World Cup hangover and consumers’ watchful spending made for a difficult environment. Nevertheless, conditions are likely to remain very challenging as we move towards the crucial final quarter of the year. A lot now hangs on the government’s Budget in October, which is a crucial opportunity to revive the confidence of consumers and hospitality alike.”“A good start to September will have been a relief to On-Premise operators and beer, cider and soft drinks brands. It has helped to claw back some of the ground that was lost in August, when extreme heatwaves, a World Cup hangover and consumers’ watchful spending made for a difficult environment. Nevertheless, conditions are likely to remain very challenging as we move towards the crucial final quarter of the year. A lot now hangs on the government’s Budget in October, which is a crucial opportunity to revive the confidence of consumers and hospitality alike.”
The Daily Drinks Tracker provides analysis of sales at managed licensed premises across Britain and is part of NIQ powered by CGA’s suite of research services delivering in-depth data on category, supplier and brand rate of sale performance.
Unlock essential On-Premise insights
Discover more about brand rate of sales performance and access the latest intelligence on drinks Understand the trends and opportunities to win across this crucial channel.